The Shelf, the Shipment and the Leaf
Leave a message
01 The shelf: margin wins the rack
Start in a convenience store, because that is where the money still changes hands. In 2025, 82.9% of US cigarette sales and 92.9% of other tobacco and nicotine sales went through convenience retail. Over the past 52 weeks cigarette revenue fell 2.5%. Smokeless alternatives, pouches mostly, grew 22.4% in value and 15.2% in volume.
Now the number a retailer actually looks at: cigarettes earn a 14.86% gross margin. Everything else on that rack earns 29.85%.
Shelf space is finite and it is allocated by margin per inch, not by loyalty. A category that is growing, paying twice the margin and taking the queue at the register does not have to argue for the space. It simply gets it.
02 The shipment: two markets, one headline
China's September exports: $819 million, the second monthly fall in a row, down $146 million on August. The United States fell 28.6% to $239 million; the United Kingdom fell 30.2% to $123 million. Between them they account for the entire net drop. Every other destination added $2.9 million, or 0.6%.
That is not the world buying less. The UK is still about 37% above September last year. The US is 37.7% below it. Same monthly direction, opposite annual stories, two different problems wearing one word.
Devices say the same thing in miniature. Volumes fell by 14.5 million units while the average declared price rose 11.9% to $4.05. Remove Slovakia, which shipped an unusual share of high-value units, and the rise is 4.9%. That is mix, not pricing power. Meanwhile the map redraws itself: UAE +44.6%, Slovakia +193%, Malaysia +31.3%, Russia +30.1%.
03 The leaf: nicotine went back inside the monopoly
On 20 October Beijing repeated a rule and widened it. Nicotine and nicotine salts used in smoke-free tobacco products must be extracted from tobacco and will be administered as cut leaf: licences, quotas, the full apparatus.
For vaping that is 2022 restated. For pouches it is new, because pouches only became regulated tobacco products in January. The finished product was already inside the monopoly. From now the ingredient is too. A mandatory national standard for pouches sits next in the queue.
04 What we do with it
■ Build for the rack, not the spec sheet. Two products pass the same test and only one gets the space. Margin per unit and turns per month decide, which is why our quotes now start with cost per use.
■ Read the mix, not the total. A market down 30% and a market up 44% are the same headline number. One needs a phone call, the other needs a production slot.
■ Nicotine is a document now. Origin and licence travel with the order. A supplier who cannot produce both is quoting you a price you cannot ship.
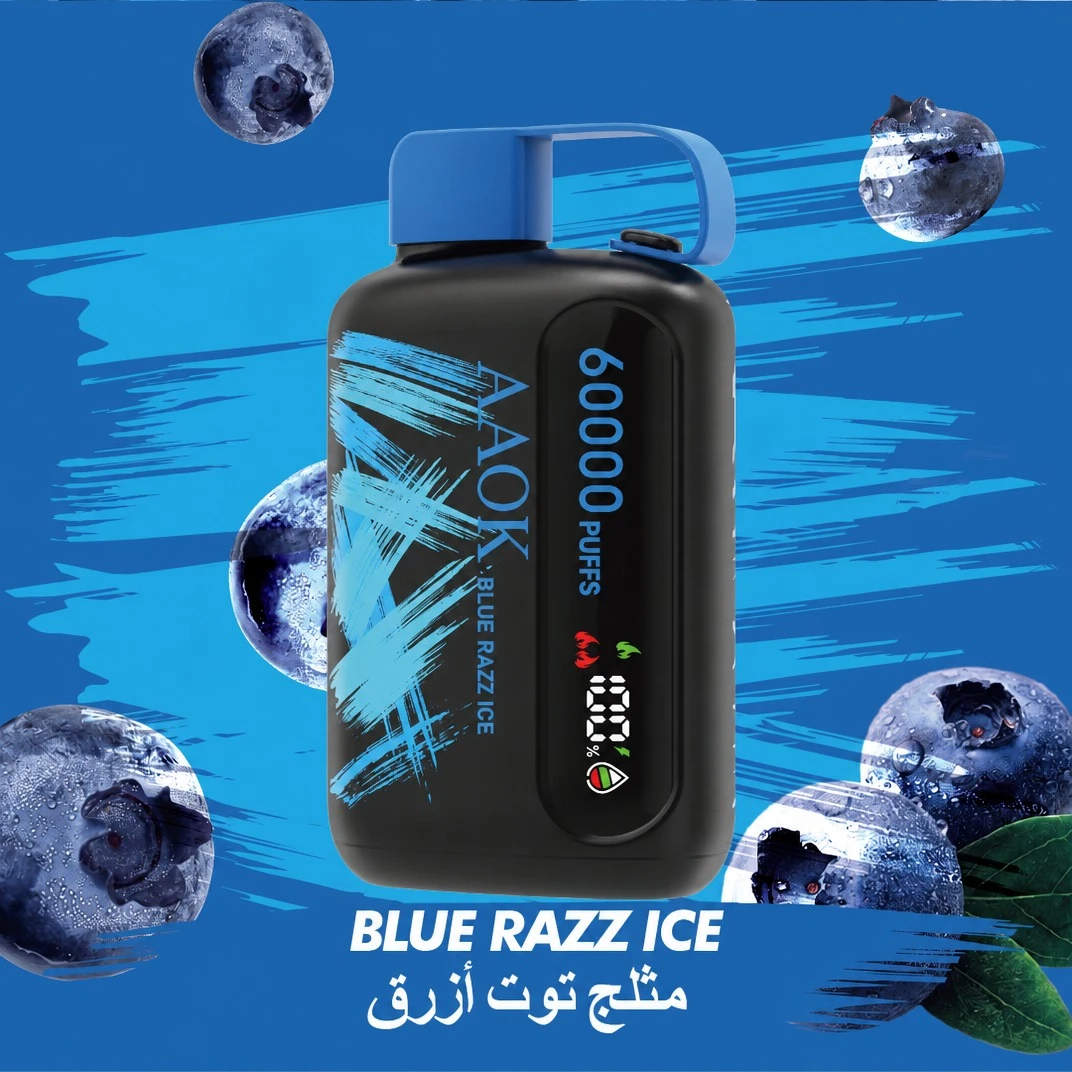
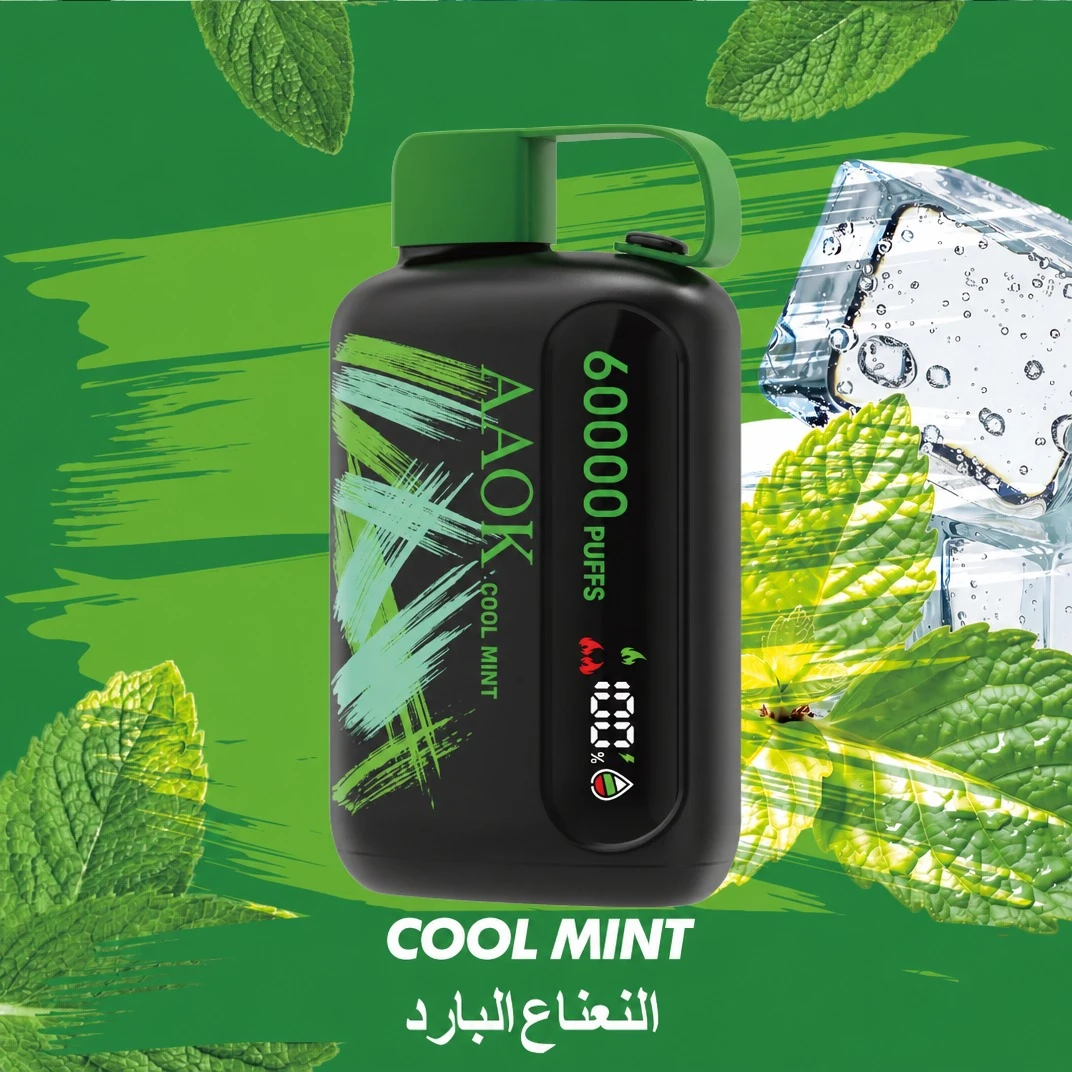
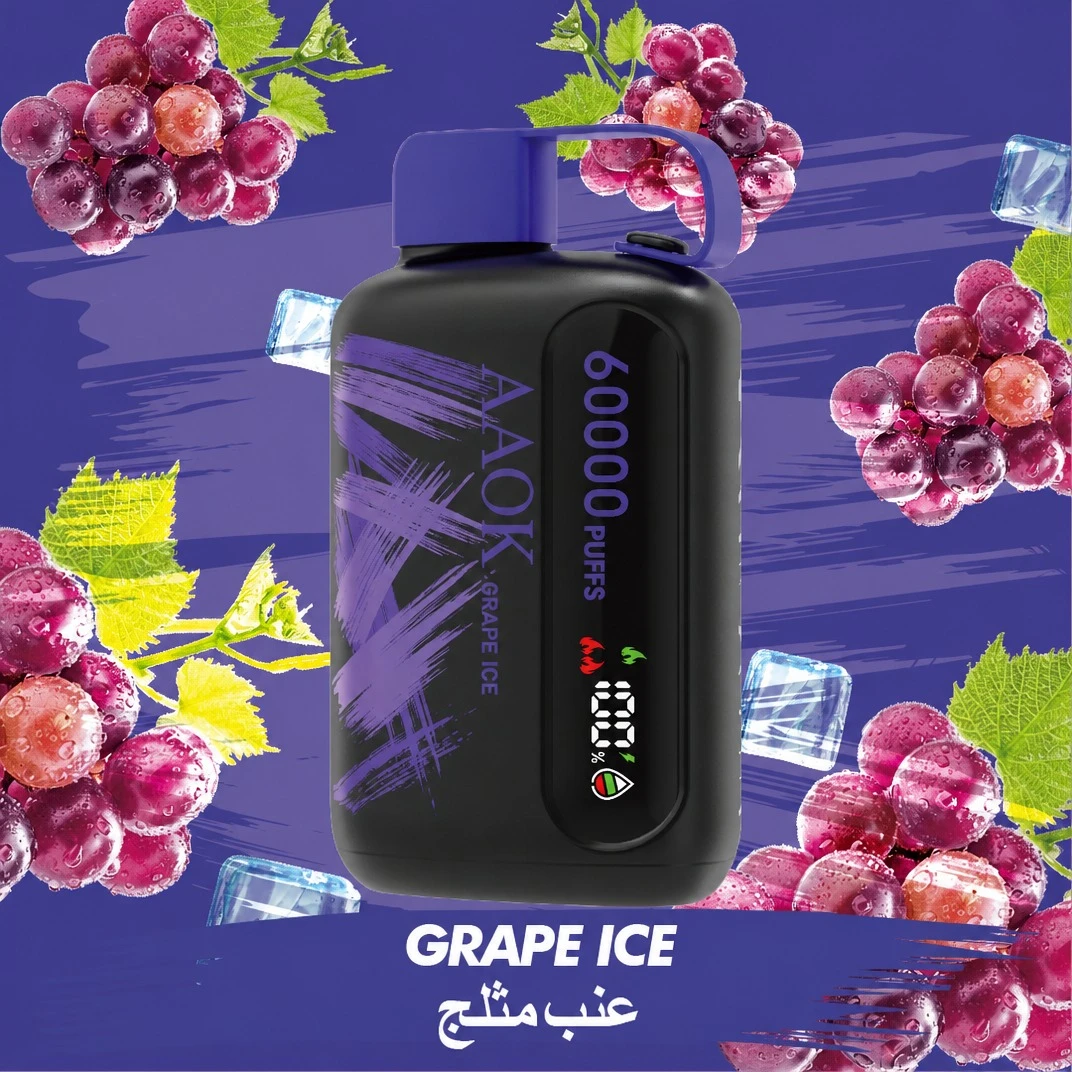
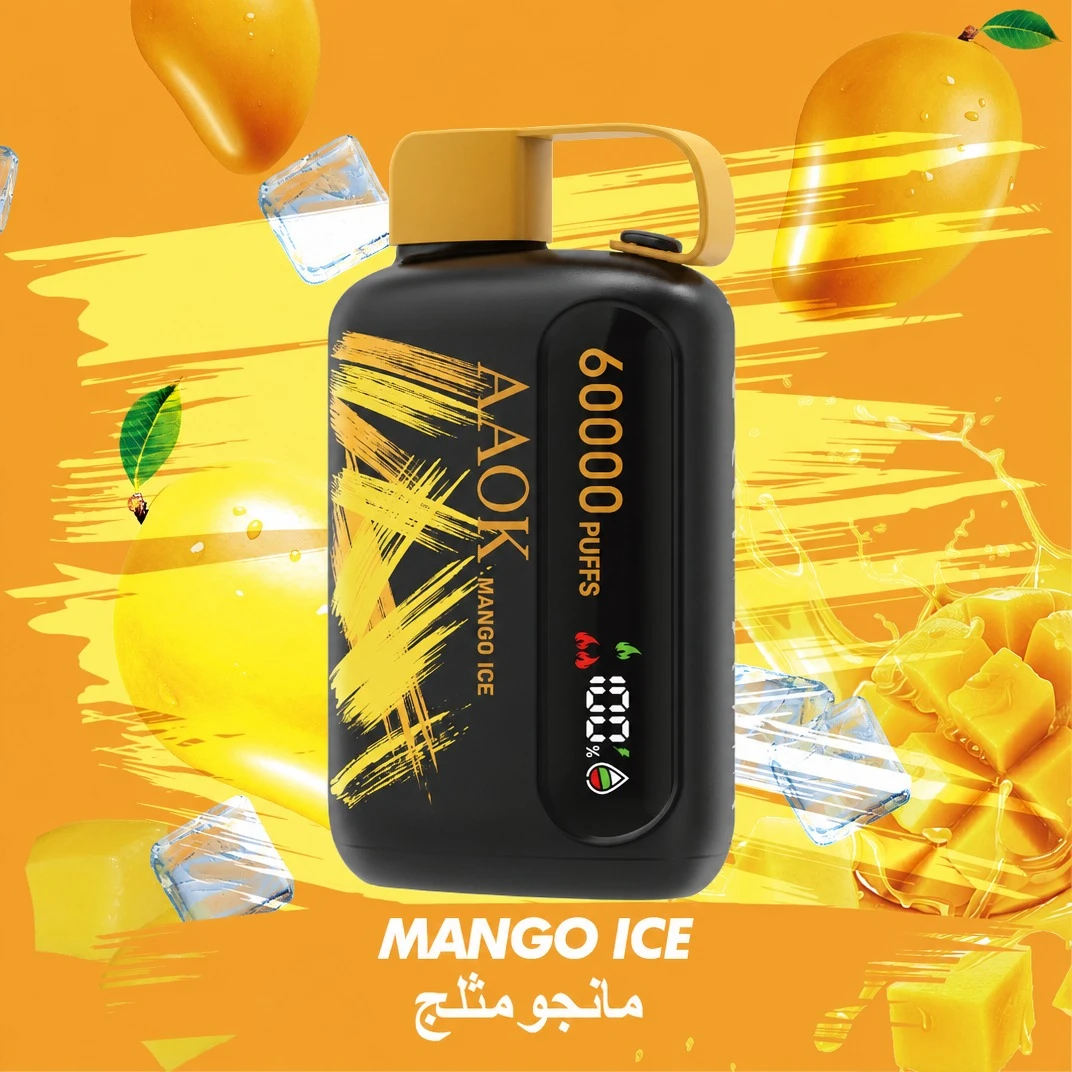
AAOK 60000 - one chassis, four flavours, Arabic retail artwork for Gulf distributors
BOTTOM LINE
The category is not shrinking. It is being re-sorted: cigarettes to pouches, two big destinations to eight smaller ones, open-market nicotine to licensed leaf. Watch the rack, not the forecast.
SOURCES
– China customs export statistics, HS 24041200 and HS 85434000, September 2026, as compiled by trade press; year-on-year figures are estimates.
– NACS / NielsenIQ US convenience retail data, 52 weeks to 2026: channel share, sales change and gross margin by category.
– State Tobacco Monopoly Administration, Announcement No. 3 of 2026 (20 October): nicotine for smoke-free products administered as cut tobacco.
For adult audiences only, where such products may lawfully be sold and advertised. Export values are not retail sales; declared unit prices are not shelf prices. Independent commentary, no investment, legal or health claim.